- voice
- India
- car market
- staring
- stagnancy
- selling
- foreign investors
- stock market
- decline
- issues
- structural
- geopolitical
- local
- global
- auto industry
- largest contributor
- GST
- exchequer
- local
- global
- nature.
Rough Road Ahead For the Indian Auto Industry?
- By Bhushan Mhapralkar
- March 12, 2025
The voice about India’s car market staring at stagnancy is growing amid much selling by foreign investors in the stock market. Auto sticks of OEMs and suppliers have taken a beating lately. The reasons for stock market decline are said to be structural issues as well as geopolitical issues. In other words, they are local as well as global in their nature. The Indian auto industry – as the largest contributor of GST to the exchequer and among the highest contributor to the country's manufacturing GPD – is also quite local and global in its ways of working.
Like any other developing nation, it is a market where the scope for an increase in automobile population is bright. It is also a market that is beset by structural issues nonetheless. With 34 cars owned per 1,000 people, the country with a population estimated to be 1,463,865,525 in 2025 has ample scope for auto sales growth.
But as banks struggle for liquidity and a reduction in repo rate by the apex bank fails to reflect in the reduction of loan interest rates or equated monthly instalments, the structural issues facing the automobile industry are too stark to overlook.
Adding to the structural issues are perhaps developments such as the recent announecement by Maharashtra Government to levy six percent motor vehicle tax on premium electric vehicles. The leading industrialised state also has among the highest road toll taxes among other Indian states. The highway network in the state is among the most lacking and unsafe. Most roads in the state have either deteriorated or are under a seemingly unending period of repairs.
The state government in its 2025 budget has also announced that it has raised the motor vehicle tax by one percentage point on individual-owned non-transport four-wheeler CNG and LPG vehicles. Such vehicles currently attract a seven to nine percent tax depending on their type and price.
While electricity costs have been rising with distribution companies like MSEDCL pushing for a revision in fixed and energy charges for various categories in order to bridge revenue gap, owning electric vehicles and CNG vehicles is becoming costlier though eco-friendlier.
Attracting over 200 percent in taxes, petrol and diesel prices have been at an all-time high. A timely upward revision in toll prices is only adding further to the cost of motoring in a country where close to or more than 50 of the vehicle purchase price amounts to taxes. Spares are also taxed at a hefty 28 percent and the labour costs have steeply risen post Covid-19 pandemic.
With vehicle prices being jacked up by automakers under the pretext of rising input costs by about four to five percent if not more, the Indian auto industry is clearly under pressure to maintain its margins and stay profitable.
Against the operating costs, the foot falls in the showroom are taking longer to realise into actual sales. Discounts are gaining speed and indicative of sales losing stream in some of the segments that were until recently doing very well.
Any excitement about a rebate in Income Tax up to INR 1,200,000 – it takes over INR 1,000,000 to purchase a decent car in India today – seeming to have faded into thin air, the talk about government announced a reduction in GST taxes has gained speed. When it would actually come into effect is yet to be known but the narrative has started building. The stock market does not look excited however and the money lost by domestic investors may take a long time to come back, it seems.
As US President Donald Trump speaks about exposing India’s ‘wrong’ tariff policies in the absence of any statement from the Indian government striking out his claims, the Indian market for automobiles and other consumer goods looks destined for a rough ride. Stagnancy will be a part of the plot, the repercussions of which would stem from domestic structural issues as well as geopolitical shifts where calls like ‘China Plus One’ hold no value at all anymore.
With the entry of Tesla – which has seen its sales and stock prices plummet in many of existing markets off late – set to enter India with the government lowering tariff under pressure from the US President, the subject of too much regulation needs to be examined in terms of structural strength and the industry’s ability to be competitive. Local manufacture is also a subject that needs to be looked at as MSME sector continues to shrink and take down with it the PMI index.
Skilling is also a subject that should be looked at as engineering courses lose interest with the young in the country. A manufacturing-less economy that is also witnessing the services sector face a slowdown – again due to structural and geopolitical issues – may not spell a good omen for growth in the long run. This, particularly in the case of a country whose median age in 29 years.
China’s ‘Deep seek’ has shown how the prowess in technology can shift overnight and highly influence the economy of a nation, its stock markets suddenly. In India, the auto industry should nurture the MSME sector as much as the government should. A services alternative in terms of growth over manufacturing may not hold forth in the long-term. Manufacturing exports can shrink abruptly anytime under the shifting regulatory and other market issues in the domestic marketplace and under the shifting geopolitical situations in various parts of the world that also make lucrative export markets.
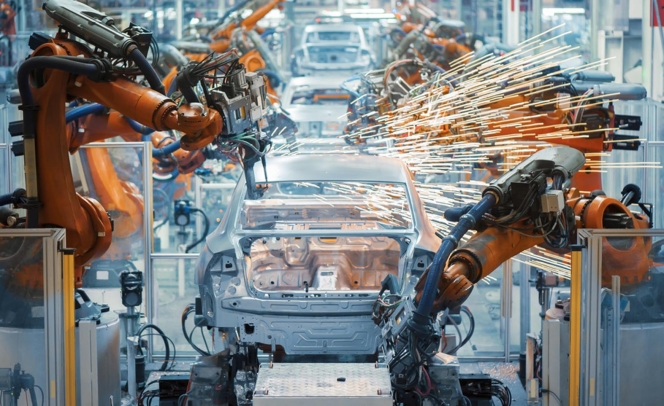
Image for representative purpose only.
AIFI’s 2nd Annual Conference Focuses On ‘China Plus One’ Opportunity For Indian Forging Sector
- By MT Bureau
- September 16, 2026
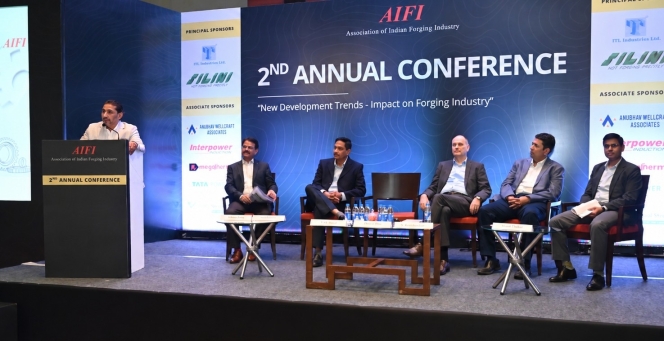
The Association of Indian Forging Industry (AIFI), the apex body of the Indian forging sector, hosted its 2nd Annual Conference on ‘New Development Trends – Impact on Forging Industry’. The event gathered leading stakeholders to discuss the evolving business environment, the China Plus One opportunity, technology and automation, productivity, manpower, rising input costs and the need for greater resilience and competitiveness.
Discussions stressed that the industry stands at a pivotal moment to strengthen its place in global value chains as companies diversify supply sources. However, it must move beyond traditional manufacturing models by investing in technology, automation, engineering, R&D, skilled manpower, productivity and sustainability. The consensus was that while India has the base, talent and market opportunity, forging firms must build capability to manage uncertainty and deliver higher-value solutions.
Chief Guest Thomas Dose, Managing Director, BMW Group Plant Chennai, highlighted India’s growing global relevance under the China Plus One strategy. He noted that geopolitical turbulence and single-supplier risks are pushing global companies to diversify, giving India a strong chance to become the preferred destination, with customers seeking greater engineering and end-to-end responsibility.
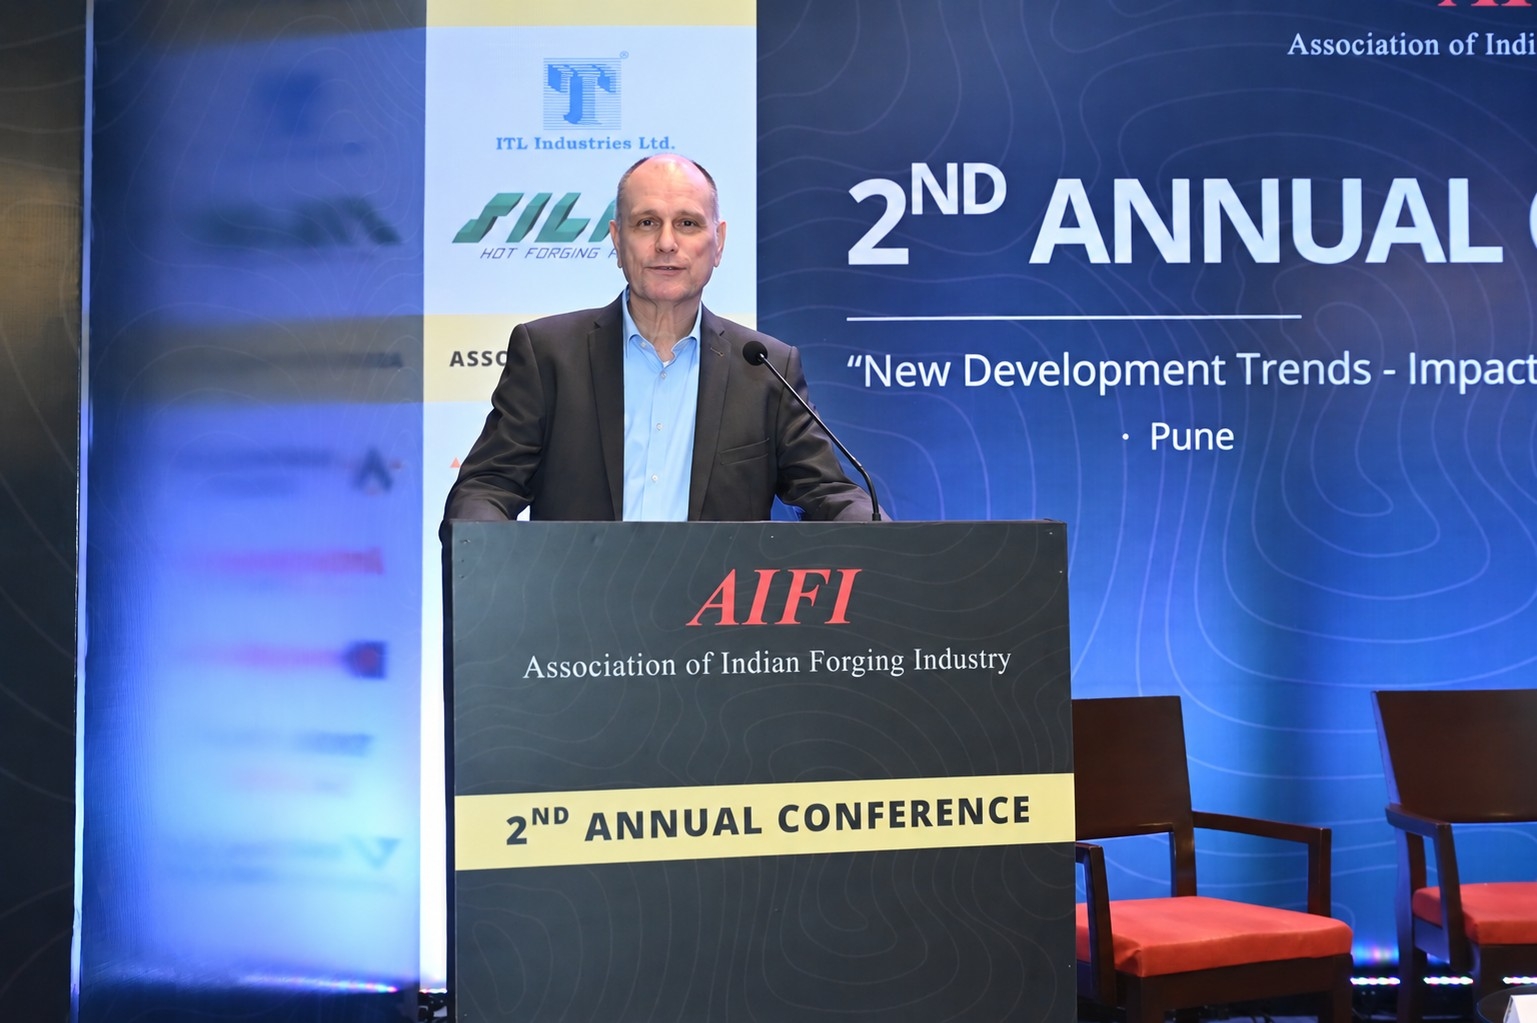
Sunil Javalekar, Chairman, Western Region, AIFI & CEO, S. B. Forgetech Pvt. Ltd., gave the welcome address. Yogesh Thakar, Executive Director, PwC, presented ‘Indian Forging Industry – Next Global Edge’. The memento presentation and vote of thanks were delivered by S Ravishankar, Vice President, AIFI & MD, Super Auto Forge Pvt. Ltd.
A panel on ‘Managing Uncertainty / Challenges to Capitalize on Demand Surge’ was moderated by S Ravishankar, with Vidyashankar Krishnan, CMD, M.M. Forgings Ltd.; Vikas Bajaj, MD, Bajaj Motors Ltd. and Sahil Jain, CEO, Hirschvogel Components India Private Limited. Discussions covered GST, manpower, automation, technology upgrades, investments, training, contingency planning, R&D, productivity, demand management and rising input costs.
The conference reinforced the industry’s significant opportunity as global supply chains evolve. AIFI continues to unite stakeholders, facilitate knowledge exchange and represent the forging fraternity, with a renewed commitment to competitiveness and growth in domestic and global markets.
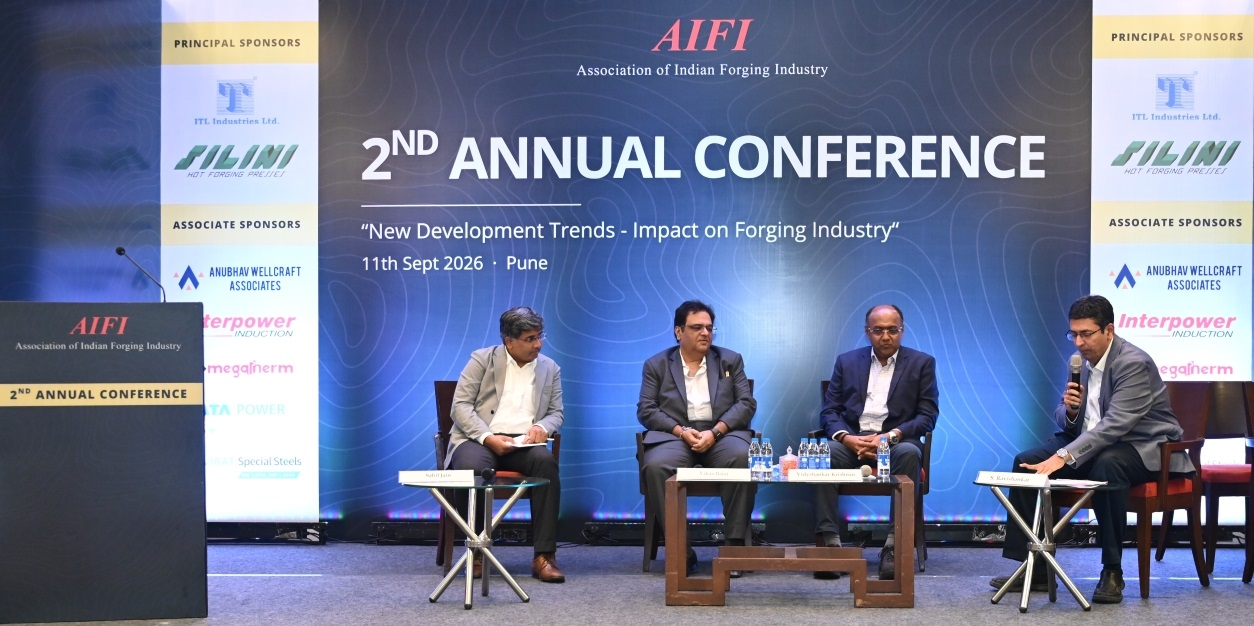
Addressing the gathering, Yash Munot, President, AIFI & CEO, Varsha Forgings Pvt. Ltd., said, “The Indian forging industry is at an important juncture, with global supply-chain realignments creating significant opportunities for India. At the same time, we must remain prepared to navigate geopolitical uncertainty, rising input costs, technology disruption and changing customer requirements. Our focus must be on increasing productivity, accelerating technology adoption, developing our people and strengthening innovation and sustainability. The opportunity before the Indian forging industry is significant, but we must build the capabilities and competitiveness required to become a stronger and more valuable partner to global customers.”
Thomas Dose, Managing Director, BMW Group Plant Chennai, said, “We believe India should be the Plus One. India has engineering talent, a large market and a very capable forging industry. But China Plus One is not only about supply; we want to see much more partnership from India. Customers are looking for capable partners who can take responsibility, contribute to engineering and development and become part of the development process. India is no longer just a supply chain; Indian companies need to be part of our development. The challenge is to connect the capabilities that are already there, and AIFI has a major role to play in this.”
High-Octane Drama And Teenage Brilliance Light Up Kari Motor Speedway
- By MT Bureau
- September 15, 2026
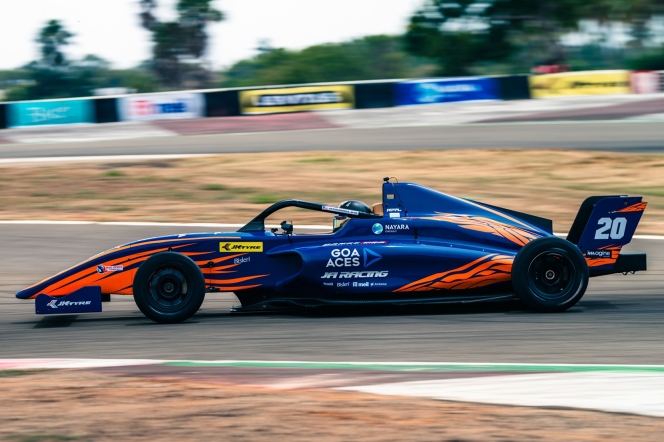
Powered by JK Tyre, the Indian Racing Festival 2026 got off to a thrilling start at the Kari Motor Speedway (KMS) in Coimbatore, recently, with the opening round of the F4 Indian Championship delivering three action-packed races and a closely contested battle for the top honours.
Aris Kyriakou emerged as the standout performer of the weekend, combining two runner-up finishes with a Race 3 victory to finish Round 1 with a dominant display.
With the opening round producing seven different drivers on the podium across the three races, the championship has already underlined the depth of competition on the grid. The F4 Indian Championship will now remain at Kari Motor Speedway for Round 2, giving the drivers another opportunity to challenge for crucial championship points at the same venue before the six-round season moves on to its other racing destinations.
South African Luviwe Sambudla stole the spotlight as the opener didn't unfold the way the grid sheet suggested it might. Sambudla, lining up eighth for Goa Aces JA Racing, tore through traffic almost immediately and had himself in podium contention within the first four opening laps in the first battle.
A mid-race safety car briefly closed up the field and threatened to undo his hard work, but it barely slowed him down as he crossed the line first in 31 minutes and 05.808 seconds, edging Kyriakou by 2.245 seconds, with pole-sitter Aaron Mehta rounding out the podium in third.
Before any of that unfolded, though, it was Mehta who'd already made headlines. The fifteen-year-old Singaporean, racing for Kolkata Royal Tigers, put in a lap of 1:05.652 to become the youngest driver ever to take pole in this championship's history. He couldn't quite hold that pace deep into the race, dropping to third as his tyres wore thin, but for a debutant barely out of his mid-teens, a podium finish is nothing to sniff at.
Aryan Narola's pole-to-flag drive made him the second-youngest race winner in series history
Starting from pole in Race 2, Goa Aces JA Racing’s Aryan Narola fended off constant pressure from Kyriakou across the full 26-lap distance on the second day of the championship, eventually taking the flag just 0.624 seconds clear. Aris Kyriakou and Swarnav Das completed the podium behind them. The result makes Narola the second-youngest winner in the championship's history, a milestone which will be talked about in the lead-up to Round Two.
Race 3 belonged to Aris Kyriakou
Starting from pole for the third race running, Kyriakou didn't have things all his own way. He crossed the line first, but not before fending off relentless pressure from Mahlori Mabunda, who spent much of the race glued to his gearbox. Third went to Mehta, while Sambudla, the weekend's Race 1 winner, could only manage fourth this time round.
Mabunda displayed the pace to challenge for the win, but spent lap after lap fighting the effects of dirty air, the turbulent, disrupted airflow that trails a car ahead and robs the chasing driver of downforce through the corners.
Further back, the race delivered its share of chaos too. With the laps winding down, the leaders began lapping the rest of the field, sweeping up everyone from fourth to fourteenth during the final 90 seconds. Amid that scramble, Ntiyiso Mabunda came to a halt on track on the last lap, forcing race control to throw a yellow flag. The timing worked out well for Mehta, who'd been running fourth behind Kyriakou and the two South Africans, but Mabunda's misfortune opened the door, and he grabbed third as a result.
Round 1 threw up seven different names on the rostrum across its three races, but it's Kyriakou's name that stands tallest heading into the next stop. With the series set to return to the very same venue for its second round, all eyes will be on whether he can carry this form forward, or whether the chasing pack finally finds a way past.
Roland Berger Study Highlights EUR 20 Trillion Tech Market Potential By 2040
- By MT Bureau
- September 12, 2026
Thirty emerging technology fields will drive global economic growth over the next 15 years, with their total market value projected to expand from EUR 2.5 trillion to more than EUR 20 trillion by 2040 says a report by global consulting firm Roland Berger.
The research titled ‘The 2040 Technology Gameplan ’ finds that these sectors will account for 37 percent of global industrial value creation by 2040, up from 9 percent today.
The study identifies 14 core technology areas as critical for industrial growth, representing a market potential of EUR 16 trillion. Semiconductors, artificial intelligence (AI) systems and data centres are projected to constitute more than half of this total. Additional sectors highlighted include energy storage, quantum technologies and humanoid robotics.
Furthermore, the report points out that Europe could capture approximately 20 percent of the global market across these 14 primary technology sectors by 2040, equivalent to EUR 3 trillion in value creation. However, European industry has lost market share to the United States and China due to scaling constraints, capital limitations and institutional complexity.
To address these challenges, the analysis outlines three approaches tailored to specific technology fields: pursuing global leadership in areas such as quantum technology, medical technology, microgrids and carbon capture; leveraging domestic demand in sectors like autonomous defence, humanoid robotics and charging infrastructure; and attracting foreign technology providers to establish local operations for large language models and next-generation semiconductors.
Felix Mogge, Partner, Roland Berger, said, "Europe faces a clear mandate for action. Policymakers and industry leaders must work together to create the right conditions for investment and scaling. Otherwise, the value creation generated by the next wave of technology trends will take place elsewhere."
The study indicates that existing European regulatory frameworks, including the AI Act, the EU Battery Regulation, and the European Chips Act, have not fully achieved their targets. The findings call for EU-wide policies to support commercial scaling, capital availability, and industrial strategy across member states.
Stefan Riederle, Partner, Roland Berger, said, "Europe has the technologies and the talent to compete for global leadership in a number of fields. The challenge now is to choose the right strategy for each technology area and secure Europe’s long-term competitiveness."
- Hero Motors
- O P Munjal Holdings
- Hero Cycles
- BMW AG
- Ducati Motor Holding
- Enviolo International
- Formula Motorsport
- Hummingbird EV
- HWA AG
Hero Motors Sets Price Band At INR 79 To INR For INR 10 Billion IPO
- By MT Bureau
- September 10, 2026
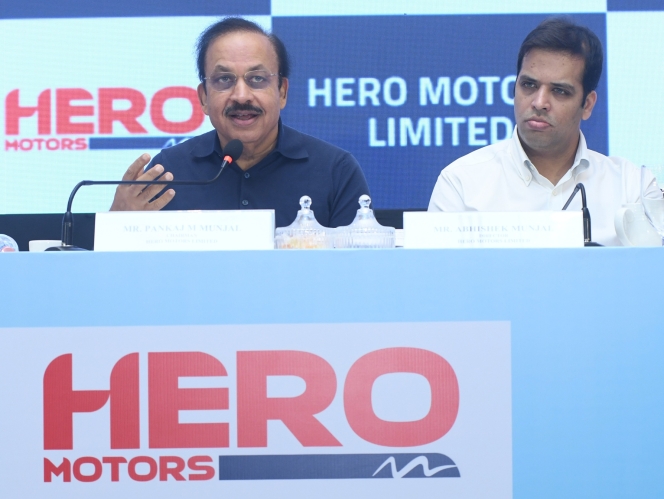
Hero Motors has fixed the price band for its initial public offering at INR 79 to INR 84 per equity share of face value INR 10 each. The offer will open for subscription on Wednesday, 16 September 2026, and close on Friday, 18 September 2026. Bidders can apply for a minimum lot of 178 equity shares and in multiples of 178 equity shares thereafter.
The company’s INR 10 billion public issue comprises a fresh issue of equity shares raising up to INR 6 billion alongside an offer-for-sale of up to INR 4 billion by promoters O P Munjal Holdings and Hero Cycles. Out of the fresh issue proceeds, the company will allocate INR 1.9 billion toward the repayment or prepayment of outstanding borrowings and INR 2 billion for capital expenditure to purchase equipment for capacity expansion at its Gautam Buddha Nagar facility in Uttar Pradesh. The remaining capital will fund inorganic growth acquisitions, strategic initiatives, and general corporate activities.
Hero Motors operates as an automotive technology company designing, developing, and manufacturing powertrain solutions for original equipment manufacturers across the United States, Europe, India and the ASEAN region. The company provides integrated system-level and component-level powertrain products, electric motors, integrated drive units, gear sets and continuously variable transmissions for electric and non-electric applications. Its client portfolio includes two-wheelers, performance cars, e-bikes, off-road vehicles, electric and hybrid automobiles, heavy-duty commercial transport, and electric vertical take-off and landing aircraft.
The company supplies global original equipment manufacturers and component firms including BMW AG, Ducati Motor Holding, Enviolo International, Formula Motorsport, Hummingbird EV and HWA AG.
The IPO is structured through the book-building process, allocating up to 50 percent of the net offer to qualified institutional buyers, a minimum of 15 percent to non-institutional bidders and a minimum of 35 percent to retail individual bidders.
Comments (0)
ADD COMMENT